Mortgage Rates Are Stuck in the High 7%s — So Why Is Irvine the One Market Where Sales Are Actually Up?
The question I hear most from clients right now is, "I heard rates came down a bit — is now a good time to buy?" The short answer: mortgage rates are still bouncing around near this year's highs, and while the California market overall is visibly cooling, Orange County and Irvine are telling a different story. Here's why, and what that means for how buyers and sellers should move right now.
Mortgage Rates Haven't Dropped — They're Just Catching Their Breath
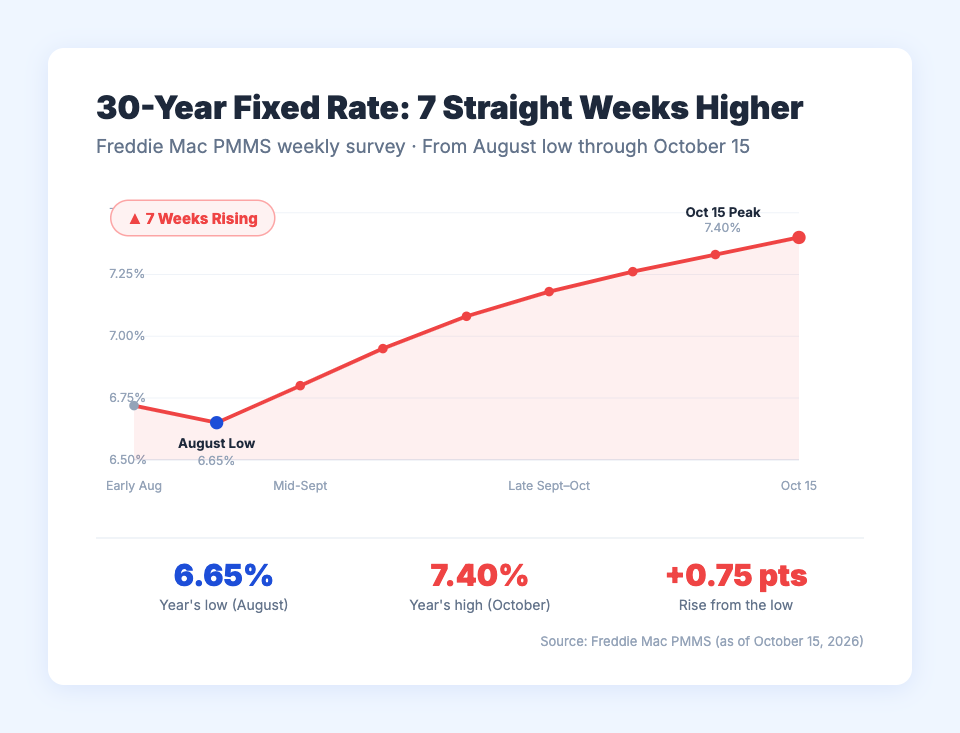
According to Freddie Mac's official weekly Primary Mortgage Market Survey (PMMS), the 30-year fixed rate fell to 6.65% in August, then climbed for seven straight weeks starting mid-September to hit this year's high of 7.40% in October. The October 15 reading held flat at 7.40%, unchanged from the week before.
The recent headlines claiming rates "dropped back into the 7.3% range" are based on daily trackers like Mortgage News Daily. Rates rose to 7.42% on October 12, eased to 7.32–7.39% on the 13th, continued drifting lower through the 14th, then bounced back up to 7.36–7.38% on the 15th after an inflation report came in hotter than expected. In other words, this isn't the start of a real decline — it's more accurate to call it a narrow back-and-forth near the yearly high as the market catches its breath. Compared to the same period a year ago (October 2025 averaged 6.27–6.30%), rates are still more than a full percentage point higher.
What matters more is the forward outlook. Fannie Mae recently revised its forecast upward, projecting 7.4% in Q4 2026 and roughly 7.5% throughout 2027. The Mortgage Bankers Association (MBA) similarly doesn't see rates dropping below 7% until at least 2027. Neither organization has a return to the 6% range anywhere in the near-term picture.
California Is Slowing Down — So Why Is Irvine Different?
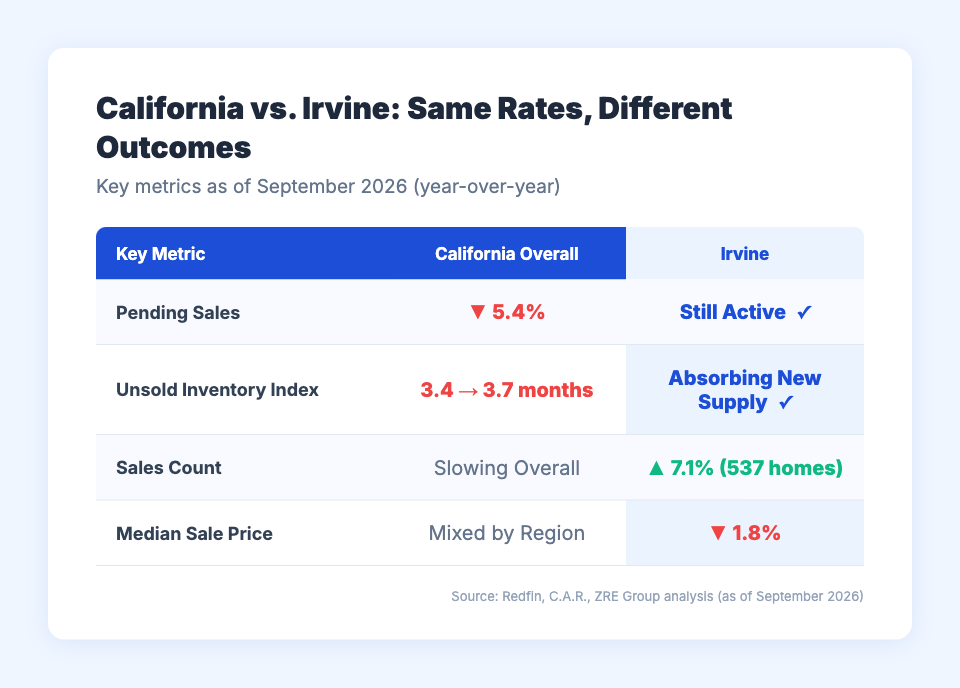
With rates holding stubbornly high, the broader California market is clearly showing signs of a slowdown. Redfin data shows September pending sales fell 5.4% year-over-year and 4% month-over-month, the largest monthly drop in three years. C.A.R. data tells the same story: the Unsold Inventory Index rose from 3.4 months in July to 3.7 months in August, meaning listings are piling up faster than they're being sold.
Irvine, however, is moving to a different beat. According to analysis from ZRE Group, Irvine's median sale price is down 1.8% year-over-year, yet the number of homes sold actually rose 7.1% to 537 transactions over the same period — more than the combined sales volume of Laguna Niguel, Laguna Beach, and Carlsbad. In other words, prices softened slightly, but buyer demand did not.
I'd describe this as "demand hasn't collapsed — rather, an increase in new supply (master-planned villages, new-construction condos and townhomes) is letting the market find a healthier balance." When I walk new Irvine developments with clients, competition isn't as fierce as it used to be, but listings are far from sitting unsold either.
That said, one thing shouldn't be overstated. Prices in high-cost areas like Irvine and Orange County genuinely are declining (roughly 2–6% depending on the source). And Orange County remains one of the least affordable markets in California — some analyses show only 15% of households can afford the median-priced home, which requires a minimum annual income of around $370,000. "Holding up" does not mean "easier to buy."
If You're a Buyer, What Should You Do Right Now?
Honestly, there's little chance rates drop dramatically anytime soon. If Fannie Mae and the MBA's forecasts hold, rates could stay above 7% through 2027. That means "waiting for rates to come down" may not be as advantageous a strategy as it sounds. While you wait, rates keep hovering in the 7% range — and in a market like Irvine where transactions are still active, the good listings may get snapped up first.
I always give clients the same three-point checklist: Can you comfortably afford the monthly payment right now? Do you plan to stay at least 5 years? And is there realistic room to refinance later if rates do fall? If all three check out, locking in a good property now can be a more practical move than waiting for rates to drop further.
Markets like Irvine — where prices have softened slightly but sales volume has held up — represent a rare window where buyers can gain some negotiating leverage even while the broader state and national market slows down. That said, the entry barrier is real, with the median price still in the $1.4M range, so matching your budget to a realistic area comes first.
If You're a Seller, What Should You Do Right Now?
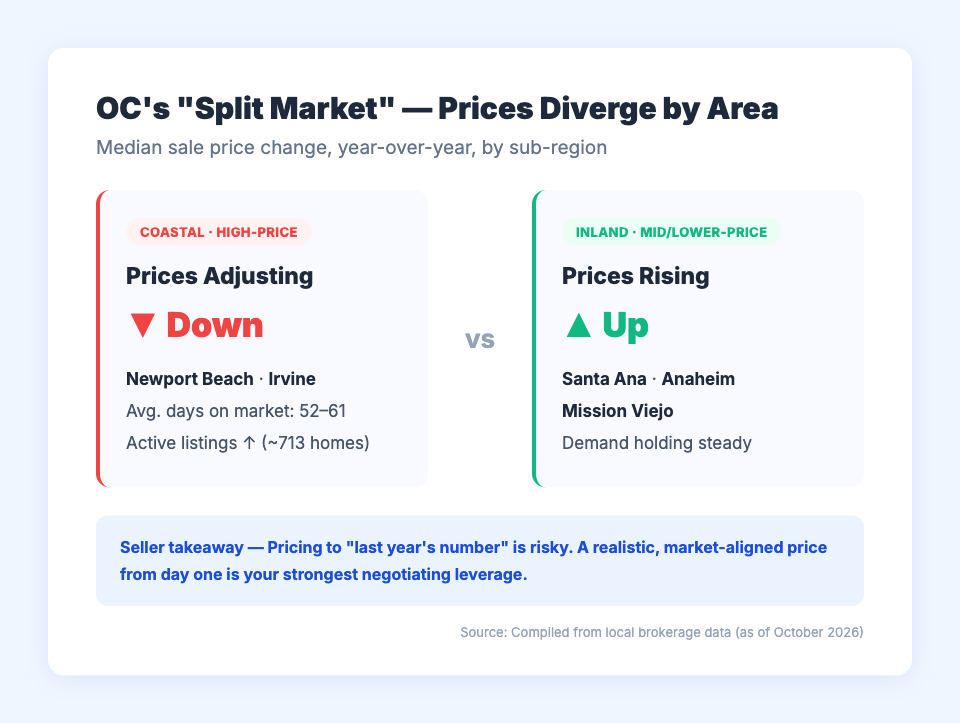
As a seller, you need to understand the "split market" dynamic at play. Coastal, higher-priced areas like Newport Beach and Irvine are seeing year-over-year price declines, while lower- and mid-priced inland areas like Santa Ana, Anaheim, and Mission Viejo are actually seeing prices rise. Your strategy should depend entirely on which side of that split your home falls on.
If you're listing in an area where prices are adjusting, like Irvine, pricing based on "last year's numbers" is risky. While transactions are still happening steadily, average days on market have stretched to 52–61 days, and active inventory has grown too (roughly 713 listings as of October). Starting with a realistic price actually leads to a faster sale on better terms. I tell sellers in this market directly: pricing it right from day one is your biggest source of negotiating power — a listing priced accurately from the start is far more attractive to buyers than one that started too high and had to come down weeks later.
To sum up: mortgage rates haven't dropped dramatically — they're bouncing around in a narrow range near this year's high. California as a whole is clearly slowing down, but Orange County and Irvine are in a relatively healthy adjustment phase, where prices have softened slightly while sales volume has actually held steady. Whether "now" is the right time to buy or sell ultimately depends on your own finances and goals, but there's little reason to make that call based on national headlines alone when this particular market is telling its own story.
If you have questions about buying or selling in California real estate — especially in Orange County and Irvine — right now, feel free to reach out in the comments or via DM. I'll give you an honest read based on what I'm seeing firsthand on the ground, from actual listings and pricing trends in this market.
Feel free to reach out anytime for buying or leasing properties in Irvine and Orange County.

Michael Kim
REAL Estate Agent
DRE# 02282988 | C&C Realty Group Inc
📞 949-517-2945
C&C REALTY GROUP
LUXURY REAL ESTATE