Mortgage Rates Hit 7.18%: Down 3 Weeks in a Row, But Still 1 Point Above Last Year
You've probably heard that mortgage rates are falling, but is it actually a good time to buy? According to Freddie Mac's November 5 release, the average 30-year fixed mortgage rate came in at 7.18%, marking three straight weeks of declines. Still, that's about 1 percentage point higher than a year ago (6.22%), so the fair way to describe it is "coming down, but not yet comfortable." In this post, I'll walk through a few key numbers and what buyers and sellers can do right now.
Where Are Rates Now? 7.18%, Down 3 Weeks in a Row
The latest Freddie Mac Primary Mortgage Market Survey (PMMS) was released on November 5. The 30-year fixed rate was 7.18% and the 15-year fixed was 6.57%. Last week (October 29) they were 7.24% and 6.60%, so the 30-year rate dropped 0.06 percentage points.
| | This Week (11/05) | Last Week (10/29) | Year Ago (2025-11-06) | |---|---|---|---| | 30-Year Fixed | 7.18% | 7.24% | 6.22% | | 15-Year Fixed | 6.57% | 6.60% | 5.50% |
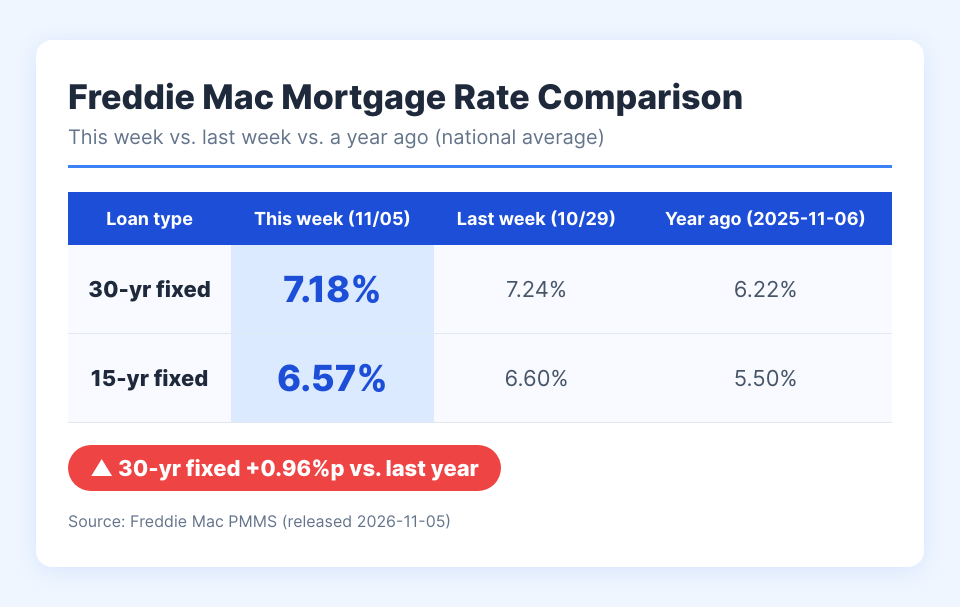
One thing to keep in mind: these figures are national averages. The quote you actually receive depends on your credit score, down payment, points, and lender. There is no official Southern California-only figure, so I'll use the national average as the benchmark here.
What Does This Rate Mean for Your Monthly Payment?
A 0.06-point move may look small on paper, but the 0.96-point gap from a year ago is significant. The example below is a hypothetical to help illustrate: an $800,000 loan, 30-year fixed, principal and interest only (excluding taxes, insurance, and HOA; actual quotes may differ).
- At 6.22%: about $4,910 per month - At 7.18%: about $5,420 per month - Difference: about $510 per month, or roughly $6,100 per year
By contrast, the difference between last week's 7.24% and this week's 7.18% is only around $30 per month under the same conditions. That's why I tell my clients: "Rather than reacting to a 0.05-point weekly move, first check whether your monthly payment fits your budget."
In high-priced areas like Irvine, loan sizes are larger, so rate changes have an even bigger effect on the monthly payment. The most accurate approach is to plug in your own loan amount, as in the example above.
If You're a Buyer: Should You Wait for Rates to Drop Further?
No one can say exactly where rates will go next. Three weeks of declines don't guarantee a fourth. Instead of waiting for a target rate, I suggest looking at two things separately:
1. Can you afford it? If the monthly payment at today's rate is comfortable, it's fine to start searching for homes. 2. Can you adjust the rate later? If rates fall, refinancing is an option. However, refinancing comes with costs and qualification requirements, so it isn't a guaranteed path.
Waiting is a valid choice, but it carries risk. When rates fall, buyers who have been on the sidelines may jump in all at once, which can mean more competition for good listings. On the other hand, Southern California sales volume has recently softened, so there may be room to negotiate. This varies by property and location, so it's best to evaluate the homes you're interested in directly.
Some practical tips: get quotes from 2 or 3 lenders and compare them, check how points and lender credits are structured, and talk through your rate lock timing in advance.
If You're a Seller: How Should You Sell in This Market?
California existing single-family home sales in September came in at an annualized 260,410 units, down 6.5% from a year earlier. Southern California fell 9.1%, the steepest decline among regions, according to reports (C.A.R. data, KPBS report dated 2026-10-19). The reports also noted that higher rates are weighing on buyer demand.
Reading these numbers, in a market with fewer buyers it pays to price realistically from the start and have your home in great shape. Here's what I recommend to my seller clients:
- Set the initial price based on recent sales in the same community or school district - Tidy up and do light repairs before photos to make a strong first impression - Consider terms that ease the buyer's monthly payment burden (such as lender credits) as a negotiating tool
I won't make blanket claims about recent price trends in Orange County or Irvine in this post. Conditions vary widely by neighborhood and community, so it's best to check the value of your specific home individually.
To sum up, the 30-year fixed rate of 7.18% has fallen for three straight weeks but remains higher than a year ago. Whether your monthly payment fits your budget matters more than small weekly rate changes. For buyers, the keys are comparing quotes and timing your rate lock; for sellers, it's realistic pricing and good preparation.
If you'd like to learn more about any topic covered here as it applies to your situation, feel free to reach out in the comments or via DM. Whether you want to explore Orange County or Irvine listings together, or wonder what a fair price would be if you sold your home today, don't hesitate to ask, and I'll answer honestly to the best of my knowledge. If rates shift after next week's Freddie Mac release, I'll be back with an update.
Sources: Freddie Mac PMMS (released 2026-11-05), RISMedia (2026-11-05), KPBS / City News Service (2026-10-19, C.A.R. September data)
Feel free to reach out anytime for buying or leasing properties in Irvine and Orange County.

Michael Kim
REAL Estate Agent
DRE# 02282988 | C&C Realty Group Inc
📞 949-517-2945
C&C REALTY GROUP
LUXURY REAL ESTATE